News/Blogs
ব্যবসার জন্য পেমেন্ট গেটওয়ে কেন প্রয়োজন?
অনলাইন পেমেন্টের ১০টি গুরুত্বপূর্ণ সুবিধা:
বাংলাদেশে অনলাইন ব্যবসা পরিচালনা করতে গেলে Product বা Service বিক্রির পাশাপাশি গ্রাহকের কাছ থেকে Payment গ্রহণের বিষয়টিও গুরুত্বের সঙ্গে বিবেচনা করতে হয়। একজন গ্রাহক আপনার Website থেকে পণ্য কিনতে আগ্রহী হলেও Payment করার সুবিধা না থাকলে তিনি Order সম্পন্ন নাও করতে পারেন। আবার Payment নেওয়ার পর সেটি যাচাই করা, হিসাব রাখা এবং নির্ধারিত সময়ে Settlement পাওয়ার বিষয়গুলোও ব্যবসার দৈনন্দিন কাজের অংশ।
আগে অনেক ব্যবসা Cash on Delivery, Bank Transfer...
...
See More →
<p><strong>অনলাইন পেমেন্টের ১০টি গুরুত্বপূর্ণ সুবিধা:</strong><br />
<br />
বাংলাদেশে অনলাইন ব্যবসা পরিচালনা করতে গেলে Product বা Service বিক্রির পাশাপাশি গ্রাহকের কাছ থেকে Payment গ্রহণের বিষয়টিও গুরুত্বের সঙ্গে বিবেচনা করতে হয়। একজন গ্রাহক আপনার Website থেকে পণ্য কিনতে আগ্রহী হলেও Payment করার সুবিধা না থাকলে তিনি Order সম্পন্ন নাও করতে পারেন। আবার Payment নেওয়ার পর সেটি যাচাই করা, হিসাব রাখা এবং নির্ধারিত সময়ে Settlement পাওয়ার বিষয়গুলোও ব্যবসার দৈনন্দিন কাজের অংশ।</p>
<p>আগে অনেক ব্যবসা Cash on Delivery, Bank Transfer কিংবা ব্যক্তিগত Mobile Financial Services (MFS) Account ব্যবহার করে Payment সংগ্রহ করত। ছোট পরিসরে এই পদ্ধতিগুলো কাজে এলেও Order ও Transaction-এর সংখ্যা বাড়লে Manual Payment Management কঠিন হয়ে উঠতে পারে।</p>
<p>এ কারণে Online Business-এর জন্য Payment Gateway একটি গুরুত্বপূর্ণ প্রযুক্তিগত সমাধান। এটি Website বা Application-এর সঙ্গে Digital Payment System যুক্ত করে, যাতে গ্রাহক বিভিন্ন Payment Method ব্যবহার করে অনলাইনে মূল্য পরিশোধ করতে পারেন।</p>
<p>তবে Payment Gateway-এর প্রয়োজন শুধু অনলাইনে টাকা গ্রহণের মধ্যে সীমাবদ্ধ নয়। এটি Payment Verification, Transaction Records, Customer Experience এবং ব্যবসার Financial Operations পরিচালনার ক্ষেত্রেও ভূমিকা রাখে।</p>
<p>এই লেখায় আলোচনা করা হবে কেন একটি ব্যবসার Payment Gateway প্রয়োজন, এটি কীভাবে দৈনন্দিন কাজের সুবিধা দিতে পারে এবং EPS Bangladesh কীভাবে বিভিন্ন ধরনের ব্যবসাকে Online Payment গ্রহণে সহায়তা করে।</p>
<h2><strong>Payment Gateway কী এবং কীভাবে কাজ করে?</strong></h2>
<p>Payment Gateway হলো এমন একটি Digital Payment Technology, যা গ্রাহক, ব্যবসায়ী এবং সংশ্লিষ্ট Bank বা Payment Network-এর মধ্যে Transaction Information আদান-প্রদানে সহায়তা করে।</p>
<p>ধরুন, একজন গ্রাহক আপনার Online Store থেকে একটি Product কিনতে চান। তিনি Product নির্বাচন করে Checkout Page-এ গেলেন। এরপর bKash, Nagad, Debit Card অথবা Credit Card-এর মতো কোনো Payment Method বেছে নিয়ে Payment সম্পন্ন করলেন।</p>
<p>এই প্রক্রিয়ায় Payment Gateway গ্রাহকের Payment Request গ্রহণ করে সংশ্লিষ্ট Payment System-এর কাছে পাঠায়। Transaction যাচাইয়ের পর Payment-এর ফলাফল Merchant Website-এ জানানো হয়।</p>
<p>একটি সাধারণ Payment Flow এভাবে কাজ করে:</p>
<ol>
<li>Customer Checkout: গ্রাহক Website থেকে Product বা Service নির্বাচন করেন।</li>
<li>Payment Selection: নিজের পছন্দের Payment Method বেছে নেন।</li>
<li>Payment Processing: Payment Gateway Transaction Information সংশ্লিষ্ট Payment Network-এ পাঠায়।</li>
<li>Authorization: Bank বা Payment Provider Transaction যাচাই করে।</li>
<li>Payment Response: Successful বা Failed Transaction-এর Status Website-এ ফেরত আসে।</li>
<li>Settlement: নির্ধারিত নিয়ম অনুযায়ী ব্যবসায়ীর Bank Account-এ অর্থ পাঠানো হয়।</li>
</ol>
<p>এই প্রক্রিয়ার ফলে গ্রাহক অনলাইনে Payment করতে পারেন এবং ব্যবসায়ী Transaction-এর তথ্য পর্যবেক্ষণ করতে পারেন।</p>
<h2><strong>ব্যবসার জন্য Payment Gateway কেন প্রয়োজন?</strong></h2>
<p>একটি ব্যবসার Payment System কেমন হবে, তা নির্ভর করে তার Customer, Product, Transaction Volume এবং Operating Process-এর ওপর। যেসব ব্যবসা অনলাইনে Payment গ্রহণ করে, তাদের জন্য Payment Gateway বেশ কয়েকটি ব্যবহারিক সুবিধা দিতে পারে।</p>
<h3><strong>১. গ্রাহকের জন্য একাধিক Payment Option দেওয়া যায়</strong></h3>
<p>সব গ্রাহক একই Payment Method ব্যবহার করেন না। কেউ bKash বা Nagad ব্যবহার করতে স্বাচ্ছন্দ্যবোধ করেন, কেউ আবার Debit Card, Credit Card কিংবা Internet Banking পছন্দ করেন।</p>
<p>আপনার Website-এ যদি মাত্র একটি Payment Option থাকে, তাহলে অন্য Method ব্যবহার করতে চান এমন গ্রাহকদের জন্য Payment করা কঠিন হতে পারে।</p>
<p>Payment Gateway-এর মাধ্যমে একাধিক Payment Channel যুক্ত করা যায়। ফলে গ্রাহক নিজের সুবিধা অনুযায়ী Payment Method নির্বাচন করতে পারেন।</p>
<p>বাংলাদেশের ব্যবসার ক্ষেত্রে সাধারণত নিচের Payment Option-গুলো গুরুত্বপূর্ণ:</p>
<ul>
<li>Mobile Financial Services: bKash, Nagad, Rocket।</li>
<li>Card Payment: Visa, Mastercard ও অন্যান্য সমর্থিত Card।</li>
<li>Internet Banking: অংশগ্রহণকারী Bank-এর Online Banking Service।</li>
</ul>
<p>একাধিক Payment Option থাকলে Checkout-এর সময় গ্রাহকের সামনে আরও বেশি পছন্দ থাকে।</p>
<h3><strong>২. Manual Payment Verification-এর কাজ কমে</strong></h3>
<p>অনেক ছোট ব্যবসা ব্যক্তিগত bKash বা Nagad Account-এ Payment গ্রহণ করে। গ্রাহক টাকা পাঠানোর পর Transaction ID বা Screenshot পাঠান। এরপর ব্যবসার কর্মীকে Account বা Statement দেখে Payment যাচাই করতে হয়।</p>
<p>প্রতিদিন কয়েকটি Payment হলে এই পদ্ধতি পরিচালনা করা সম্ভব। কিন্তু প্রতিদিন ৫০, ১০০ বা তার বেশি Order এলে প্রতিটি Payment আলাদাভাবে যাচাই করা সময়সাপেক্ষ হয়ে যায়।</p>
<p>Integrated Payment Gateway-এর মাধ্যমে Transaction Status System থেকে দেখা যায়। এতে Manual Verification-এর ওপর নির্ভরতা কমতে পারে।</p>
<p>উদাহরণ হিসেবে, কোনো গ্রাহক Online Course কিনলে Payment সফল হয়েছে কি না, তা Merchant Dashboard থেকে যাচাই করা যায়। Website-এর সঙ্গে সঠিক Integration থাকলে Payment Confirmation-এর পর সংশ্লিষ্ট Order বা Service Access-ও স্বয়ংক্রিয়ভাবে আপডেট করা সম্ভব।</p>
<h3><strong>৩. Checkout Process সহজ হয়</strong></h3>
<p>Online Shopping-এর ক্ষেত্রে Checkout Process গ্রাহকের সিদ্ধান্তে গুরুত্বপূর্ণ ভূমিকা রাখে। Product নির্বাচন করার পর Payment করতে গিয়ে যদি গ্রাহককে একাধিক ধাপ অনুসরণ করতে হয়, আলাদা Account-এ টাকা পাঠাতে হয় বা Payment Confirmation-এর জন্য অপেক্ষা করতে হয়, তাহলে তিনি Order সম্পন্ন না-ও করতে পারেন।</p>
<p>Payment Gateway Website-এর Checkout Process-এর সঙ্গে Payment System যুক্ত করে। এতে গ্রাহক একই Platform থেকে Payment-এর ধাপগুলো সম্পন্ন করতে পারেন।</p>
<p>একটি ভালো Checkout Experience-এর জন্য কয়েকটি বিষয় গুরুত্বপূর্ণ:</p>
<ul>
<li>পরিষ্কার Payment Instructions।</li>
<li>সহজে বোঝা যায় এমন Payment Option।</li>
<li>Mobile ও Desktop-এ ব্যবহারযোগ্য Payment Page।</li>
<li>Payment সম্পন্ন হলে Confirmation Message।</li>
<li>ব্যর্থ Transaction-এর ক্ষেত্রে পরিষ্কার Status।</li>
</ul>
<p>এসব বিষয় গ্রাহকের জন্য Payment Process বোঝা সহজ করে।</p>
<h3><strong>৪. Transaction Records এক জায়গায় রাখা যায়</strong></h3>
<p>ব্যবসার প্রতিটি Payment-এর হিসাব রাখা জরুরি। কোন Order-এর জন্য কত টাকা এসেছে, কোন Payment সফল হয়েছে এবং কোন Transaction ব্যর্থ হয়েছে—এসব তথ্য Financial Management-এর অংশ।</p>
<p>Manual Payment Collection-এর ক্ষেত্রে তথ্য বিভিন্ন Mobile Account, Bank Statement, Spreadsheet অথবা Message-এর মধ্যে ছড়িয়ে থাকতে পারে।</p>
<p>Payment Gateway-এর Merchant Dashboard থেকে Transaction History এবং Payment Status দেখা যায়। এতে ব্যবসার Payment Records পর্যালোচনা করা সহজ হয়।</p>
<p>বিশেষ করে যেসব ব্যবসায় প্রতিদিন অনেক Transaction হয়, তাদের জন্য এই সুবিধা গুরুত্বপূর্ণ।</p>
<h3><strong>৫. Payment Status দ্রুত যাচাই করা যায়</strong></h3>
<p>একটি সাধারণ ব্যবসায় গ্রাহক Payment করার পর অনেক সময় প্রশ্ন করেন, “আমার টাকা কি পেয়েছেন?” Payment Gateway ব্যবহারের ফলে Merchant Dashboard থেকে সংশ্লিষ্ট Transaction Status পরীক্ষা করা যায়।</p>
<p>যেমন:</p>
<ul>
<li>Successful Payment</li>
<li>Failed Transaction</li>
<li>Pending Transaction</li>
<li>Refund Status</li>
</ul>
<p>এতে গ্রাহকের Payment-সংক্রান্ত প্রশ্নের উত্তর দিতে ব্যবসার কর্মীদের সুবিধা হয়।</p>
<p>তবে কোনো Transaction Pending থাকলে সেটিকে Successful ধরে নেওয়া উচিত নয়। সংশ্লিষ্ট Payment Status নিশ্চিত করে পরবর্তী ব্যবস্থা নিতে হবে।</p>
<h3><strong>৬. ব্যবসার Payment Management সহজ হয়</strong></h3>
<p>ব্যবসার অর্ডার ও Payment-এর সংখ্যা বাড়লে শুধু টাকা গ্রহণ করাই যথেষ্ট নয়। প্রতিটি Payment-এর সঙ্গে Order, Customer এবং Product Information মিলিয়ে দেখার প্রয়োজন হয়।</p>
<p>Payment Gateway-এর API Integration-এর মাধ্যমে Website বা Business Software-এর সঙ্গে Payment System যুক্ত করা যায়।</p>
<p>উদাহরণ হিসেবে:</p>
<ul>
<li>Payment সফল হলে Order Status আপডেট করা।</li>
<li>Course Fee পরিশোধ হলে শিক্ষার্থীর Access চালু করা।</li>
<li>Payment Confirmation অনুযায়ী Invoice তৈরি করা।</li>
<li>Transaction Reference সংরক্ষণ করা।</li>
<li>নির্দিষ্ট Payment Status অনুযায়ী Notification পাঠানো।</li>
</ul>
<p>এই ধরনের Integration ব্যবসার নিজস্ব Software ও Operating Process অনুযায়ী তৈরি করা যায়। ফলে Payment Management-এর অনেক কাজ System-এর মাধ্যমে পরিচালনা করা সম্ভব হয়।</p>
<h3><strong>৭. অনলাইন ব্যবসার জন্য ২৪/৭ Payment গ্রহণের সুযোগ</strong></h3>
<p>একটি Physical Store-এর নির্দিষ্ট Opening ও Closing Time থাকে। কিন্তু Website বা Online Platform থেকে গ্রাহক যেকোনো সময় Product বা Service দেখতে পারেন।</p>
<p>Payment Gateway যুক্ত থাকলে ব্যবসার অনুমোদিত Payment Channel সচল থাকা সাপেক্ষে গ্রাহক দিনের বিভিন্ন সময়ে Online Payment করতে পারেন।</p>
<p>ধরুন, একজন গ্রাহক রাত ১২টায় আপনার Website থেকে একটি Training Course কিনতে চান। Payment System চালু থাকলে তাঁকে পরের দিন অফিস খোলা পর্যন্ত অপেক্ষা করতে হয় না।</p>
<p>এটি বিশেষভাবে কাজে আসে:</p>
<ul>
<li>Online Course Platform</li>
<li>E-commerce Website</li>
<li>Subscription Service</li>
<li>Digital Product Store</li>
<li>Online Booking Platform</li>
</ul>
<p>তবে Payment গ্রহণের সুযোগ থাকলেই সব ব্যবসায় স্বয়ংক্রিয়ভাবে ২৪/৭ Customer Support বা Service Delivery নিশ্চিত হয় না। সেগুলো আলাদাভাবে পরিচালনা করতে হয়।</p>
<h3><strong>৮. ব্যবসার Financial Reconciliation সহজ হয়</strong></h3>
<p>Financial Reconciliation হলো ব্যবসার হিসাবের সঙ্গে Payment Transaction এবং Bank Settlement-এর তথ্য মিলিয়ে দেখা।</p>
<p>ধরুন, আপনার Website-এ এক দিনে ১০০টি Successful Payment হয়েছে। কিন্তু Bank Account-এ Settlement এসেছে নির্ধারিত সময়ে বা নির্দিষ্ট Batch অনুযায়ী। তখন কোন Transaction-এর অর্থ কোন Settlement-এর অন্তর্ভুক্ত, তা যাচাই করতে হয়।</p>
<p>Payment Gateway-এর Transaction Records ও Settlement Information এই কাজের জন্য সহায়ক হতে পারে।</p>
<p>এতে ব্যবসা নিচের বিষয়গুলো পরীক্ষা করতে পারে:</p>
<ul>
<li>মোট Successful Transaction।</li>
<li>Transaction Amount।</li>
<li>Payment Date ও Reference।</li>
<li>Settlement Information।</li>
<li>Refund বা Failed Transaction-এর তথ্য।</li>
</ul>
<p>ব্যবসার Accounting Team এসব তথ্য ব্যবহার করে Financial Records মিলিয়ে দেখতে পারে। তবে Payment Gateway-এর Dashboard নিজে থেকে পূর্ণাঙ্গ Accounting System-এর বিকল্প নয়।</p>
<h3><strong>৯. ব্যবসার বিভিন্ন ধরনের Payment গ্রহণ করা যায়</strong></h3>
<p>সব ব্যবসার Payment Collection-এর ধরন এক নয়। কোনো ব্যবসা Product বিক্রি করে, কোনো প্রতিষ্ঠান Course Fee সংগ্রহ করে, আবার কোনো Service Provider Client-এর কাছ থেকে Consultation Fee গ্রহণ করে।</p>
<p>Payment Gateway বিভিন্ন ধরনের ব্যবসার Online Payment Collection-এর প্রয়োজন অনুযায়ী ব্যবহার করা যায়।</p>
<p> </p>
<table cellspacing="0" style="border-collapse:collapse; width:507px">
<tbody>
<tr>
<td style="border-bottom:1px solid #000000; border-left:1px solid #000000; border-right:1px solid #000000; border-top:1px solid #000000; vertical-align:top; width:124px">
<p><strong>ব্যবসার ধরন</strong></p>
</td>
<td style="border-bottom:1px solid #000000; border-left:1px solid #000000; border-right:1px solid #000000; border-top:1px solid #000000; vertical-align:top; width:383px">
<p><strong>Payment Collection-এর উদাহরণ</strong></p>
</td>
</tr>
<tr>
<td style="border-bottom:1px solid #000000; border-left:1px solid #000000; border-right:1px solid #000000; border-top:1px solid #000000; vertical-align:top; width:124px">
<p>E-commerce</p>
</td>
<td style="border-bottom:1px solid #000000; border-left:1px solid #000000; border-right:1px solid #000000; border-top:1px solid #000000; vertical-align:top; width:383px">
<p>Product-এর মূল্য গ্রহণ</p>
</td>
</tr>
<tr>
<td style="border-bottom:1px solid #000000; border-left:1px solid #000000; border-right:1px solid #000000; border-top:1px solid #000000; vertical-align:top; width:124px">
<p>E-learning</p>
</td>
<td style="border-bottom:1px solid #000000; border-left:1px solid #000000; border-right:1px solid #000000; border-top:1px solid #000000; vertical-align:top; width:383px">
<p>Course ও Training Fee</p>
</td>
</tr>
<tr>
<td style="border-bottom:1px solid #000000; border-left:1px solid #000000; border-right:1px solid #000000; border-top:1px solid #000000; vertical-align:top; width:124px">
<p>Education</p>
</td>
<td style="border-bottom:1px solid #000000; border-left:1px solid #000000; border-right:1px solid #000000; border-top:1px solid #000000; vertical-align:top; width:383px">
<p>School, College ও Institute Fee</p>
</td>
</tr>
<tr>
<td style="border-bottom:1px solid #000000; border-left:1px solid #000000; border-right:1px solid #000000; border-top:1px solid #000000; vertical-align:top; width:124px">
<p>Consultancy</p>
</td>
<td style="border-bottom:1px solid #000000; border-left:1px solid #000000; border-right:1px solid #000000; border-top:1px solid #000000; vertical-align:top; width:383px">
<p>Consultation Fee ও Service Charge</p>
</td>
</tr>
<tr>
<td style="border-bottom:1px solid #000000; border-left:1px solid #000000; border-right:1px solid #000000; border-top:1px solid #000000; vertical-align:top; width:124px">
<p>Healthcare</p>
</td>
<td style="border-bottom:1px solid #000000; border-left:1px solid #000000; border-right:1px solid #000000; border-top:1px solid #000000; vertical-align:top; width:383px">
<p>Hospital ও Diagnostic Bill</p>
</td>
</tr>
<tr>
<td style="border-bottom:1px solid #000000; border-left:1px solid #000000; border-right:1px solid #000000; border-top:1px solid #000000; vertical-align:top; width:124px">
<p>Restaurant</p>
</td>
<td style="border-bottom:1px solid #000000; border-left:1px solid #000000; border-right:1px solid #000000; border-top:1px solid #000000; vertical-align:top; width:383px">
<p>Online Food Order</p>
</td>
</tr>
<tr>
<td style="border-bottom:1px solid #000000; border-left:1px solid #000000; border-right:1px solid #000000; border-top:1px solid #000000; vertical-align:top; width:124px">
<p>Retail</p>
</td>
<td style="border-bottom:1px solid #000000; border-left:1px solid #000000; border-right:1px solid #000000; border-top:1px solid #000000; vertical-align:top; width:383px">
<p>দোকানের Product Payment</p>
</td>
</tr>
<tr>
<td style="border-bottom:1px solid #000000; border-left:1px solid #000000; border-right:1px solid #000000; border-top:1px solid #000000; vertical-align:top; width:124px">
<p>NGO</p>
</td>
<td style="border-bottom:1px solid #000000; border-left:1px solid #000000; border-right:1px solid #000000; border-top:1px solid #000000; vertical-align:top; width:383px">
<p>Donation Collection</p>
</td>
</tr>
<tr>
<td style="border-bottom:1px solid #000000; border-left:1px solid #000000; border-right:1px solid #000000; border-top:1px solid #000000; vertical-align:top; width:124px">
<p>Software ও SaaS</p>
</td>
<td style="border-bottom:1px solid #000000; border-left:1px solid #000000; border-right:1px solid #000000; border-top:1px solid #000000; vertical-align:top; width:383px">
<p>Subscription Fee</p>
</td>
</tr>
</tbody>
</table>
<p>ব্যবসার ধরন অনুযায়ী Payment Flow ও Integration Requirement ভিন্ন হতে পারে। তাই Gateway নির্বাচন করার আগে নিজের Business Model বিবেচনা করা জরুরি।</p>
<h3><strong>১০. ব্যবসার জন্য একটি নির্দিষ্ট Payment Infrastructure তৈরি হয়</strong></h3>
<p>ব্যবসা বড় হওয়ার সঙ্গে সঙ্গে Payment Collection-এর জন্য আলাদা আলাদা Account ও Manual Process পরিচালনা করা কঠিন হতে পারে।</p>
<p>একটি Integrated Payment Gateway ব্যবসার Website, Payment Channel এবং Transaction Management-এর মধ্যে সংযোগ তৈরি করে।</p>
<p>এর ফলে ব্যবসা একটি নির্দিষ্ট System-এর মাধ্যমে Payment গ্রহণ, Status যাচাই এবং Transaction Records পর্যবেক্ষণ করতে পারে।</p>
<p>বিশেষ করে একাধিক Product, Service বা Business Location পরিচালনা করা প্রতিষ্ঠানের ক্ষেত্রে এই ধরনের Payment Infrastructure গুরুত্বপূর্ণ হতে পারে।</p>
<p><br />
</p>
<h2><strong>EPS Bangladesh কীভাবে ব্যবসাকে Online Payment গ্রহণে সহায়তা করে?</strong></h2>
<p>বাংলাদেশের ব্যবসার জন্য একটি Payment Gateway নির্বাচন করার সময় Payment Method, Integration সুবিধা, Merchant Dashboard, Transaction Management এবং Customer Support বিবেচনা করা জরুরি।</p>
<p>EPS Bangladesh বিভিন্ন ধরনের ব্যবসাকে Online Payment গ্রহণের সুবিধা প্রদান করে। এর মাধ্যমে Merchant-রা Website বা Online Platform-এর সঙ্গে একাধিক Payment Channel যুক্ত করতে পারেন।</p>
<p>EPS-এর Payment Solution-এ ব্যবসার ধরন ও Merchant Approval অনুযায়ী নিচের Payment Method পাওয়ার সুযোগ রয়েছে:</p>
<ul>
<li>Mobile Financial Services: bKash, Nagad, Rocket, OK Wallet, MyCash ও ekpay।</li>
<li>Card Payment: Visa, Mastercard, American Express এবং অন্যান্য সমর্থিত Card।</li>
<li>Internet Banking: অংশগ্রহণকারী Bank-এর Internet Banking Service।</li>
</ul>
<p>EPS-এর Service এবং ব্যবসার জন্য দেওয়া Payment Solution সম্পর্কে বিস্তারিত জানতে<a href="https://eps.com.bd/"> EPS Bangladesh-এর Website</a> ভিজিট করতে পারেন।</p>
<h3><strong>EPS Merchant Registration Process</strong></h3>
<p>EPS Payment Gateway ব্যবহার করতে আগ্রহী ব্যবসাকে প্রথমে Merchant হিসেবে Registration করতে হয়। সাধারণত প্রক্রিয়াটি কয়েকটি ধাপে সম্পন্ন হয়।</p>
<p>১. Merchant Registration Form পূরণ</p>
<p>প্রথমে ব্যবসার নাম, Business Category, Contact Information, Address এবং Website URL-সহ প্রয়োজনীয় তথ্য দিয়ে Registration আবেদন করতে হয়।</p>
<p>২. Business Documents জমা</p>
<p>ব্যবসার পরিচয় ও বৈধতা যাচাইয়ের জন্য প্রয়োজনীয় Document জমা দিতে হয়। যেমন:</p>
<ul>
<li>Trade License</li>
<li>TIN Certificate</li>
<li>Business Owner-এর NID</li>
<li>সাম্প্রতিক ছবি</li>
<li>Business Logo</li>
<li>Bank Account Information</li>
<li>Website ও Business Address</li>
</ul>
<p>৩. Business Verification</p>
<p>EPS-এর সংশ্লিষ্ট Team জমা দেওয়া তথ্য ও Document যাচাই করে। ব্যবসার ধরন অনুযায়ী অতিরিক্ত তথ্য বা Document প্রয়োজন হতে পারে।</p>
<p>৪. Technical Integration</p>
<p>Verification সম্পন্ন হলে Website বা Application-এর সঙ্গে Payment Gateway যুক্ত করার প্রক্রিয়া শুরু হয়। Developer API Documentation অনুসরণ করে Integration করতে পারেন।</p>
<p>৫. Sandbox Testing ও Live Activation</p>
<p>Live Payment চালুর আগে Test Environment-এ Payment Flow পরীক্ষা করা হয়। প্রয়োজনীয় Testing ও Approval শেষ হলে Live Payment গ্রহণের ব্যবস্থা চালু করা যায়।</p>
<p>Merchant Registration-এর আগে Website সচল রাখা এবং Privacy Policy ও Refund Policy Page তৈরি করা ভালো। এতে Business Verification ও Technical Review-এর সময় প্রয়োজনীয় তথ্য পাওয়া সহজ হয়।</p>
<h3><strong>EPS Merchant Dashboard</strong></h3>
<p>Payment Gateway ব্যবহারের পর Transaction পর্যবেক্ষণের জন্য Merchant Dashboard একটি গুরুত্বপূর্ণ অংশ।</p>
<p>EPS Merchant Dashboard থেকে Merchant-রা প্রাসঙ্গিক Transaction ও Settlement Information দেখতে পারেন। এর মাধ্যমে:</p>
<ul>
<li>Successful ও Failed Transaction পরীক্ষা করা যায়।</li>
<li>Payment History দেখা যায়।</li>
<li>Transaction Status যাচাই করা যায়।</li>
<li>Settlement-সংক্রান্ত তথ্য পর্যবেক্ষণ করা যায়।</li>
<li>Merchant Account-এর তথ্য পর্যালোচনা করা যায়।</li>
</ul>
<p>ব্যবসার Payment Records নিয়মিত পরীক্ষা করার জন্য এই ধরনের Dashboard সহায়ক।</p>
<h2><strong>Payment Gateway নির্বাচন করার আগে কোন বিষয়গুলো দেখবেন?</strong></h2>
<p>সব Payment Gateway সব ধরনের ব্যবসার জন্য একই রকম উপযুক্ত নয়। তাই কোনো Service গ্রহণের আগে কয়েকটি বিষয় যাচাই করা উচিত।</p>
<p>১. Transaction Fee: প্রতিটি Payment-এর জন্য কত Charge দিতে হবে এবং অন্য কোনো Setup Fee আছে কি না জেনে নিন।</p>
<p>২. Settlement Time: Successful Payment-এর অর্থ ব্যবসার Bank Account-এ জমা হতে কত সময় লাগে, তা নিশ্চিত করুন।</p>
<p>৩. Payment Methods: আপনার গ্রাহকেরা যেসব Payment Method ব্যবহার করেন, সেগুলো Gateway-তে রয়েছে কি না দেখুন।</p>
<p>৪. Integration Support: Website, WordPress বা Custom Application-এর সঙ্গে Integration করার সুবিধা ও Technical Support সম্পর্কে জানুন।</p>
<p>৫. Refund Policy: Refund Request কীভাবে পরিচালিত হয় এবং অর্থ ফেরত পেতে কত সময় লাগে, তা বুঝে নিন।</p>
<p>৬. Security: Data Encryption, Authentication, Transaction Monitoring এবং প্রযোজ্য Security Standards সম্পর্কে তথ্য যাচাই করুন।</p>
<p>৭. Customer Support: Payment Failed, Pending Transaction বা Integration সমস্যা হলে কোথায় যোগাযোগ করবেন, তা আগে থেকেই জেনে রাখুন।</p>
<p>এই বিষয়গুলো বিবেচনা করলে ব্যবসার প্রয়োজন অনুযায়ী Payment Gateway নির্বাচন করা সহজ হয়।</p>
<h2><strong>ছোট ব্যবসারও কি Payment Gateway প্রয়োজন?</strong></h2>
<p>Payment Gateway শুধু বড় E-commerce প্রতিষ্ঠানের জন্য নয়। ছোট ব্যবসা, Online Course Creator, Consultancy Firm কিংবা নতুন Digital Service Provider-ও এর সুবিধা নিতে পারেন।</p>
<p>ধরুন, আপনি Facebook Page-এর মাধ্যমে Product বিক্রি করেন। গ্রাহকের কাছ থেকে ব্যক্তিগত Account-এ Payment নেওয়ার পরিবর্তে একটি নির্দিষ্ট Payment System ব্যবহার করলে Transaction Records পরিচালনা করা সহজ হতে পারে।</p>
<p>একইভাবে, একজন Course Creator Website থেকে Course Fee সংগ্রহ করতে পারেন। Consultancy Business Online-এ Service Charge নিতে পারে। আবার একটি Subscription Platform নির্দিষ্ট Service-এর Payment গ্রহণ করতে পারে।</p>
<p>তবে Payment Gateway নেওয়ার আগে ব্যবসার Transaction Volume, Customer Base, Service Charge এবং Technical Requirement বিবেচনা করা উচিত। ব্যবসার পরিসর ছোট হলে শুরুতে Payment Gateway-এর খরচ ও সুবিধার মধ্যে সামঞ্জস্য আছে কি না, সেটিও যাচাই করুন।</p>
<h2><strong>ব্যবসার Payment System পরিকল্পিতভাবে পরিচালনা করুন</strong></h2>
<p>একটি ব্যবসার জন্য Payment Gateway প্রয়োজন শুধু অনলাইনে টাকা গ্রহণ করার কারণে নয়। এর মাধ্যমে গ্রাহকের জন্য একাধিক Payment Option রাখা, Transaction Status যাচাই, Payment Records সংরক্ষণ এবং Website-এর সঙ্গে Payment System যুক্ত করার সুযোগ তৈরি হয়।</p>
<p>বিশেষ করে E-commerce, E-learning, Consultancy, Healthcare, Retail এবং Subscription-based Business-এর ক্ষেত্রে Digital Payment Collection দৈনন্দিন কার্যক্রমের অংশ।</p>
<p>EPS Bangladesh বিভিন্ন Industry-এর ব্যবসাকে Online Payment গ্রহণের সুযোগ দেয়। Merchant Registration থেকে শুরু করে Payment Gateway Integration এবং Transaction Management পর্যন্ত ব্যবসার প্রয়োজন অনুযায়ী Service ব্যবহার করা যেতে পারে।</p>
<p>আপনার ব্যবসার জন্য EPS-এর Payment Solution সম্পর্কে আরও জানতে About EPS Bangladesh পেজটি দেখুন। Merchant Registration, Supported Payment Methods, Transaction Fee এবং Settlement Terms সম্পর্কে বিস্তারিত জেনে আপনার ব্যবসার জন্য উপযুক্ত Payment ব্যবস্থা শুরু করুন।</p>
<p> </p>
See less
Posted on November 01, 2026
Key Payment Reporting Requirements for Financial Technology Businesses
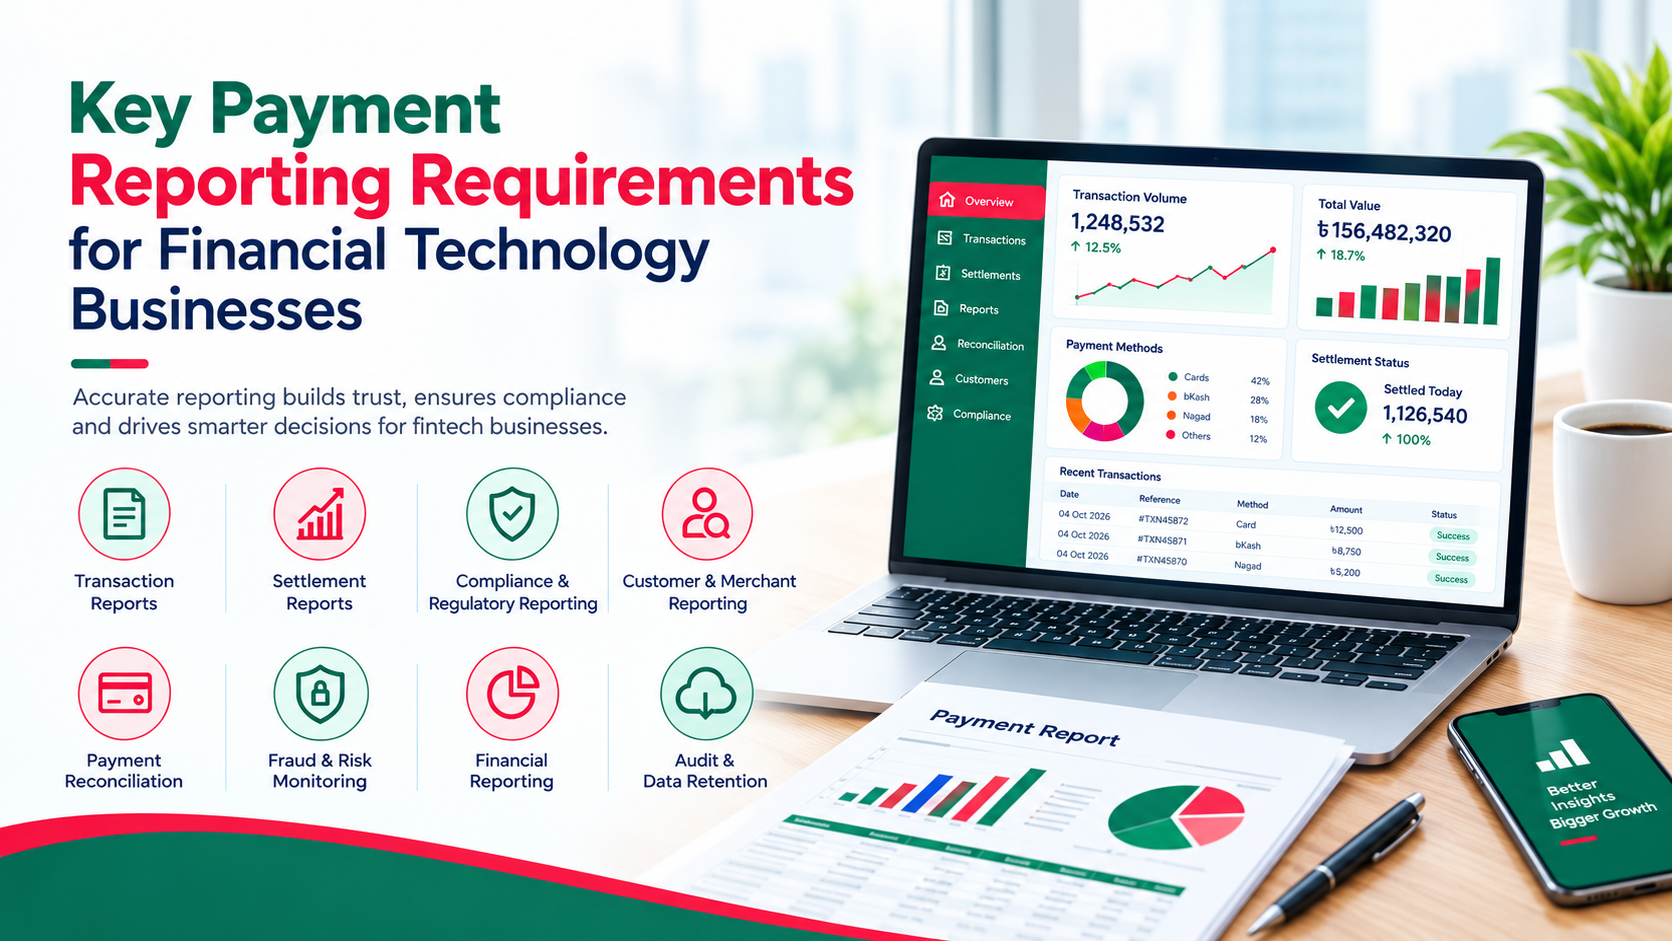
Payment reporting is a core part of financial technology operations. Every digital transaction creates information that a business may need to review, verify, reconcile or present during an audit. For fintech companies, accurate reporting helps finance teams understand transaction activity, identify payment issues and maintain clear financial records.
A payment report should do more than show how much money entered or left an account. It should explain the transaction date, payment channel, a...
...
See More →
<p>Payment reporting is a core part of financial technology operations. Every digital transaction creates information that a business may need to review, verify, reconcile or present during an audit. For fintech companies, accurate reporting helps finance teams understand transaction activity, identify payment issues and maintain clear financial records.</p>
<p>A payment report should do more than show how much money entered or left an account. It should explain the transaction date, payment channel, amount, status, fees, settlement details and any related adjustments. Businesses using an<a href="https://eps.com.bd/"> online payment gateway in Bangladesh</a> need to consider how payment information moves between customers, merchants, banks and payment service platforms.</p>
<p>Reporting requirements vary according to a company's licence, services, business model, transaction channels and applicable regulatory obligations. A payment service provider, digital wallet operator, payment gateway, lending platform and fintech software company may not all have the same reporting duties. Each business should identify the rules that apply to its activities before setting up its reporting process.</p>
<h2><strong>Why Payment Reporting Matters for Fintech Businesses</strong></h2>
<p>Fintech companies often process transactions through several channels. A single business may accept card payments, mobile financial service payments, bank transfers, QR payments and other digital payment options. Without consistent reporting, finance teams may struggle to match transaction records with bank statements and settlement information.</p>
<p>A structured reporting process helps businesses:</p>
<ul>
<li>Track incoming and outgoing transactions.</li>
<li>Identify pending, failed, reversed and refunded payments.</li>
<li>Compare transaction values with settlement amounts.</li>
<li>Review service charges and other deductions.</li>
<li>Prepare records for internal checks and external audits.</li>
<li>Respond to customer and merchant payment queries.</li>
</ul>
<p>For example, a fintech company processing 20,000 transactions in a month needs more than a monthly sales total. Its finance team may need transaction-level records to investigate a disputed payment, confirm a refund or explain a difference between the gross transaction value and the amount received after fees.</p>
<h2><strong>1. Transaction-Level Reporting</strong></h2>
<p>Transaction-level reporting is the foundation of payment records. Each payment should have a unique reference number so that the finance team can identify it without relying only on customer names or payment dates.</p>
<p>A standard transaction report should contain:</p>
<ul>
<li>Transaction ID and order or invoice reference.</li>
<li>Date and time of payment.</li>
<li>Transaction amount and currency.</li>
<li>Payment channel and payment status.</li>
<li>Merchant or customer reference.</li>
<li>Applicable fees, charges and taxes.</li>
<li>Refund, reversal or adjustment details, where relevant.</li>
</ul>
<p>Payment status needs particular attention. A transaction marked as initiated is not necessarily completed. Similarly, a pending transaction should not be treated as settled revenue until its final status has been confirmed.</p>
<p>Fintech businesses should maintain records of successful, failed, cancelled, pending and reversed transactions. This distinction helps prevent incorrect financial totals and reduces confusion when customers contact the support team.</p>
<h2><strong>2. Settlement and Reconciliation Reports</strong></h2>
<p>Transaction reporting and settlement reporting serve different purposes. A transaction report shows what customers attempted or completed through a payment channel. A settlement report shows how much money was transferred to the relevant merchant or business account.</p>
<p>Finance teams should compare the following information:</p>
<ul>
<li>Total successful transaction value.</li>
<li>Refunds and reversed payments.</li>
<li>Payment processing charges.</li>
<li>Other applicable deductions.</li>
<li>Net settlement amount.</li>
<li>Actual bank credit and settlement date.</li>
</ul>
<p>Consider a fintech platform that records BDT 500,000 in successful payments during a reporting period. If BDT 15,000 is refunded and BDT 5,000 is deducted in service charges, the expected net settlement would be BDT 480,000, assuming there are no other adjustments.</p>
<p>A reconciliation report should explain each difference between the expected and actual settlement. It should also identify transactions that remain unsettled beyond the normal processing period.</p>
<p>Businesses looking for<a href="https://eps.com.bd/about-us"> payment gateway service provider in Bangladesh</a> can review the provider's reporting facilities, settlement process and transaction information before making a decision.</p>
<h2><strong>3. Customer Verification and KYC Records</strong></h2>
<p>Know Your Customer (KYC) records help financial businesses establish who is using their services. Customer verification is particularly relevant to regulated fintech operations, digital wallets and payment services that maintain customer accounts or process financial transactions.</p>
<p>Depending on the business model and applicable rules, records may include:</p>
<ul>
<li>Customer identity and contact information.</li>
<li>National identity or other accepted identification details.</li>
<li>Business registration and ownership information for merchants.</li>
<li>Verification date and verification status.</li>
<li>Risk classification and review history.</li>
<li>Records of changes to customer information.</li>
</ul>
<p>KYC reporting should also show whether required verification steps have been completed. If a customer or merchant has not completed a required verification process, the system should make that status visible to authorised employees.</p>
<p>Fintech companies should restrict access to sensitive customer information. Reports shared with management or external reviewers should contain only the information required for their purpose.</p>
<h2><strong>4. AML and Suspicious Transaction Reporting</strong></h2>
<p>Anti-Money Laundering (AML) and Counter-Terrorist Financing (CFT) obligations are relevant to regulated financial businesses. Payment records can help compliance teams identify unusual transaction patterns, review customer activity and investigate potential financial crime.</p>
<p>Examples of activity that may require review include:</p>
<ul>
<li>Repeated transactions that do not match a customer's normal activity.</li>
<li>Unusual transaction amounts or frequency.</li>
<li>Multiple transactions that appear to be structured to avoid attention.</li>
<li>Payments involving unexpected accounts or counterparties.</li>
<li>Attempts to use incomplete or inconsistent customer information.</li>
</ul>
<p>A suspicious transaction report is not the same as an ordinary payment report. It requires a separate review and reporting process under the applicable regulatory instructions. Businesses should maintain internal procedures for identifying, escalating and documenting suspicious activity.</p>
<p>In Bangladesh, the Bangladesh Financial Intelligence Unit (BFIU) receives suspicious transaction and suspicious activity reports from reporting organisations. It also issues guidance and supervises compliance with relevant anti-money laundering requirements. The reporting duties depend on the organisation's status and applicable rules.</p>
<h2><strong>5. Trust Account, Settlement Account and Liability Reporting</strong></h2>
<p>For relevant licensed payment service providers, reporting may extend beyond individual customer transactions. Businesses may also need to maintain information about customer funds, settlement accounts, e-money balances and merchant liabilities.</p>
<p>These records help show whether the funds and liabilities recorded in the payment system agree with the balances held through the relevant banking arrangements.</p>
<p>A reporting framework may include:</p>
<ul>
<li>Trust and settlement account balances.</li>
<li>Funds received but not yet settled.</li>
<li>Merchant balances and outstanding liabilities.</li>
<li>E-money balances, where applicable.</li>
<li>Transfers, adjustments and investment information where permitted.</li>
<li>Differences between recorded liabilities and available funds.</li>
</ul>
<p>Bangladesh Bank issued a reporting direction in January 2026 covering daily information on trust and settlement accounts, funds in transit, investments from trust accounts and e-money or merchant liabilities for specified licensed entities. The direction also set a monthly submission deadline using a designated reporting format. Businesses within its scope should review the actual circular and subsequent instructions before setting their reporting calendar.</p>
<h2><strong>6. Financial Statements and Audit Reports</strong></h2>
<p>Payment reporting should connect with the company's accounting records. Finance teams need to make sure that payment income, service charges, refunds, operating expenses and outstanding balances are reflected correctly in financial statements.</p>
<p>Common financial reports include:</p>
<ul>
<li>Daily and monthly transaction summaries.</li>
<li>Revenue and service charge reports.</li>
<li>Settlement and bank reconciliation statements.</li>
<li>Refund and chargeback summaries.</li>
<li>Outstanding merchant and customer balances.</li>
<li>Financial statements and supporting schedules.</li>
</ul>
<p>For licensed Payment System Operators (PSOs) and Payment Service Providers (PSPs), applicable reporting and disclosure obligations should be checked against Bangladesh Bank's current regulations and licence conditions. The Bangladesh Payment and Settlement Systems Regulations include annual reporting and audited financial statement provisions for licensed PSOs and PSPs.</p>
<p>An audit-ready record should show where each figure came from. Finance teams should be able to trace a reported amount back to the original transaction, settlement entry, bank statement or adjustment record.</p>
<h2><strong>7. Failed Payments, Refunds and Dispute Reports</strong></h2>
<p>Failed payments and disputes require their own reporting process. A fintech company may record a payment as unsuccessful even though the customer sees a debit notification from their bank or wallet. Such cases need investigation and a clear record of the final outcome.</p>
<p>A dispute report should include:</p>
<ul>
<li>Transaction reference and date.</li>
<li>Customer or merchant complaint details.</li>
<li>Payment channel and reported issue.</li>
<li>Investigation status.</li>
<li>Refund or reversal information.</li>
<li>Resolution date and responsible team.</li>
</ul>
<p>Regular review of these reports can help management identify recurring issues with a particular payment channel, bank connection or technical process.</p>
<h2><strong>8. Operational and Risk Reporting</strong></h2>
<p>Payment reporting also covers incidents that affect the availability, security or reliability of payment services. Fintech companies should document service interruptions, system errors, security incidents and other operational issues according to their internal policies and applicable regulatory instructions.</p>
<p>Useful operational reports may cover:</p>
<ul>
<li>Payment service downtime and affected channels.</li>
<li>Failed transaction rates.</li>
<li>Delayed settlement cases.</li>
<li>Unusual system activity.</li>
<li>Security incidents and investigation records.</li>
<li>Corrective actions and incident closure dates.</li>
</ul>
<p>For example, if a technical interruption affects 800 payment attempts, the company should record the time of the incident, affected services, transaction outcomes and steps taken to resolve the issue. This information helps management assess operational risks and respond to future incidents.</p>
<h2><strong>How Fintech Companies Can Improve Their Reporting Process</strong></h2>
<p>A reporting process needs clear ownership, consistent data and regular review. Companies should avoid depending on separate spreadsheets maintained by different departments without a common reporting standard.</p>
<p>The following practices can help:</p>
<ul>
<li><strong>Set a reporting schedule:</strong> Decide which reports are required daily, weekly, monthly, quarterly or annually. Match submission dates with applicable regulatory deadlines.</li>
<li><strong>Use consistent transaction references:</strong> Maintain unique IDs across payment, settlement, refund and accounting records.</li>
<li><strong>Assign reporting responsibilities:</strong> Define which teams prepare, review and approve each report. Finance, compliance, operations and technology teams may have different responsibilities.</li>
<li><strong>Keep an audit trail:</strong> Record report preparation dates, changes, approvals and supporting documents.</li>
<li><strong>Review data quality:</strong> Check missing transaction IDs, duplicate entries, incorrect amounts and inconsistent payment statuses before submitting reports.</li>
<li><strong>Protect sensitive information:</strong> Apply access controls and secure storage for customer, merchant and transaction records.</li>
</ul>
<h2><strong>Choosing Payment Technology With Reporting Requirements in Mind</strong></h2>
<p>A payment platform should do more than process customer transactions. Fintech businesses need access to clear payment records that support daily accounting, settlement checks and financial reviews. Before selecting a provider, companies should assess transaction reporting, refund records, settlement details and data access for authorised employees.</p>
<p>When comparing the<a href="https://eps.com.bd/fintech-payment-solutions?utm_source=chatgpt.com"> Fintech Payment Gateway Solutions in Bangladesh</a>, businesses should check whether the available reporting features match their transaction volume, payment channels and internal accounting requirements.</p>
<p>The platform should also fit the company's existing financial processes. Clear transaction references, downloadable reports and reliable settlement information can help finance teams investigate discrepancies and prepare records for audits. A payment solution should support these tasks while meeting the business's security and compliance requirements.</p>
<h2><strong>Conclusion</strong></h2>
<p>Payment reporting gives fintech businesses a record of what happened at each stage of a financial transaction. From transaction details and settlement statements to customer verification, suspicious activity and audit records, each report serves a specific purpose.</p>
<p>For fintech companies in Bangladesh, the reporting process should reflect the services they provide and the regulatory obligations that apply to them. Clear reporting responsibilities, accurate transaction data, regular reconciliation and secure record-keeping can help finance and compliance teams maintain better control over payment operations.</p>
<p>EPS Bangladesh provides payment solutions for businesses that need digital payment facilities. Fintech companies can review its services and discuss their business requirements at EPS Bangladesh.</p>
See less
Posted on October 25, 2026
Digital Payment Reconciliation Between Procurement and Finance Teams
Procurement and finance teams are closely connected when it comes to business payments. Procurement handles purchase orders, suppliers, invoices, and delivery records, while finance reviews payment requests, releases funds, records expenses, and checks financial statements. When these two teams work with separate records, even a simple supplier payment can create confusion.
A digital payment process can make transaction information easier to record and review. Businesses using an online payme...
...
See More →
<p>Procurement and finance teams are closely connected when it comes to business payments. Procurement handles purchase orders, suppliers, invoices, and delivery records, while finance reviews payment requests, releases funds, records expenses, and checks financial statements. When these two teams work with separate records, even a simple supplier payment can create confusion.</p>
<p>A digital payment process can make transaction information easier to record and review. Businesses using an<a href="https://eps.com.bd/"> online payment gateway in Bangladesh</a> can maintain digital transaction details that help finance teams compare payment records with invoices and approved purchases.</p>
<p>The main purpose of payment reconciliation is simple: the business should be able to confirm that the right supplier was paid the right amount for an approved purchase. This requires cooperation between procurement and finance, along with clear records for every transaction.</p>
<h2><strong>What Is Digital Payment Reconciliation?</strong></h2>
<p>Digital payment reconciliation is the process of comparing payment transactions with the documents and records connected to those payments.</p>
<p>For a supplier transaction, this can involve checking:</p>
<ul>
<li>Purchase order</li>
<li>Supplier invoice</li>
<li>Delivery or service confirmation</li>
<li>Approved payment amount</li>
<li>Payment transaction</li>
<li>Accounting entry</li>
<li>Bank or settlement record</li>
</ul>
<p>For example, a company may issue a purchase order for ৳300,000. The supplier sends an invoice for ৳300,000, the goods are received, and finance releases the payment. During reconciliation, the team checks whether all these records agree.</p>
<p>If the payment record shows ৳280,000 while the invoice shows ৳300,000, the difference needs to be investigated. It could be a partial payment, deduction, adjustment, or recording mistake.</p>
<h2><strong>Why Procurement and Finance Need the Same Payment Information</strong></h2>
<p>Procurement and finance may have different responsibilities, but both teams need accurate transaction information.</p>
<p>Procurement needs to know whether a supplier has been paid. Finance needs to know why the payment was made and whether the amount was approved.</p>
<p>Without a shared process, businesses can face problems such as:</p>
<ul>
<li>Duplicate supplier payments</li>
<li>Incorrect payment amounts</li>
<li>Missing invoices</li>
<li>Unmatched purchase orders</li>
<li>Delayed supplier settlements</li>
<li>Unclear payment status</li>
<li>Repeated requests for transaction information</li>
</ul>
<p>These issues can become harder to manage as transaction volume increases.</p>
<p>For example, a business processing 500 supplier invoices every month may have only a small number of transactions requiring manual investigation. Yet if each unresolved case takes 15–20 minutes to review, the accumulated staff time can become substantial.</p>
<p>The figures above are illustrative examples, not industry statistics.</p>
<h2><strong>1. Create a Standard Reconciliation Process</strong></h2>
<p>The first step is to define what procurement and finance should check before and after a payment.</p>
<p>A basic process can look like this:</p>
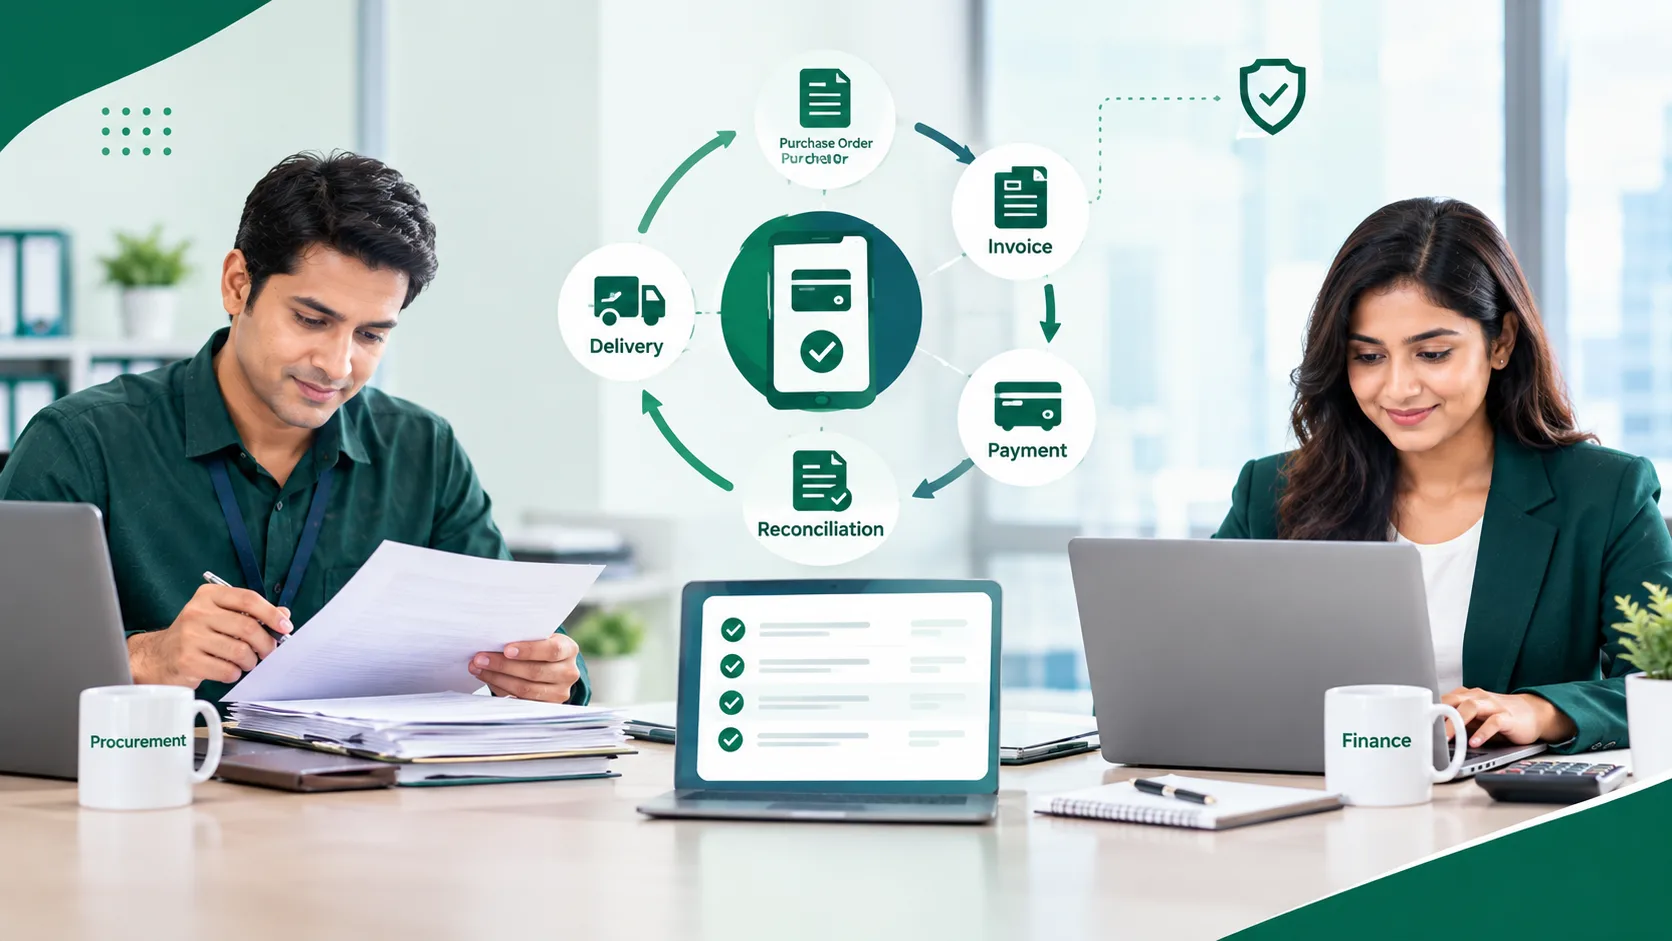
<p><strong>Purchase Order → Invoice → Delivery Confirmation → Approval → Payment → Reconciliation</strong></p>
<p>Procurement verifies the purchase and supplier information. The receiving team confirms the goods or services. Finance checks the invoice and approval before processing payment. After payment, the transaction is matched with the relevant records.</p>
<p>This structure gives each department a clear responsibility.</p>
<p>Businesses should also decide how exceptions will be handled. Partial deliveries, advance payments, invoice corrections, credit notes, and disputed invoices should have separate procedures.</p>
<h2><strong>2. Match Purchase Orders With Supplier Invoices</strong></h2>
<p>Invoice matching is one of the main parts of payment reconciliation.</p>
<p>Suppose a company orders 200 units at ৳1,500 per unit. The purchase order shows a total value of ৳300,000. The supplier invoice should be checked against the agreed quantity and price.</p>
<p>If the invoice shows 220 units, procurement should confirm whether the additional quantity was approved. Finance should not rely only on the invoice amount when releasing the payment.</p>
<p>This type of checking can identify:</p>
<ul>
<li>Incorrect quantities</li>
<li>Price differences</li>
<li>Unauthorized purchases</li>
<li>Duplicate invoices</li>
<li>Incorrect supplier details</li>
<li>Missing purchase orders</li>
</ul>
<p>For larger businesses, having a consistent invoice reference makes this process easier.</p>
<h2><strong>3. Maintain a Central Payment Register</strong></h2>
<p>A central payment register gives procurement and finance a common reference point.</p>
<p>The register can contain:</p>
<table cellspacing="0" style="border-collapse:collapse; width:569px">
<tbody>
<tr>
<td style="vertical-align:top; width:241px">
<p><strong>Information</strong></p>
</td>
<td style="vertical-align:top; width:328px">
<p><strong>Purpose</strong></p>
</td>
</tr>
<tr>
<td style="vertical-align:top; width:241px">
<p>Supplier name</p>
</td>
<td style="vertical-align:top; width:328px">
<p>Identifies the payee</p>
</td>
</tr>
<tr>
<td style="vertical-align:top; width:241px">
<p>Purchase order number</p>
</td>
<td style="vertical-align:top; width:328px">
<p>Connects payment with procurement</p>
</td>
</tr>
<tr>
<td style="vertical-align:top; width:241px">
<p>Invoice number</p>
</td>
<td style="vertical-align:top; width:328px">
<p>Identifies the supplier bill</p>
</td>
</tr>
<tr>
<td style="vertical-align:top; width:241px">
<p>Approved amount</p>
</td>
<td style="vertical-align:top; width:328px">
<p>Shows the authorized value</p>
</td>
</tr>
<tr>
<td style="vertical-align:top; width:241px">
<p>Transaction reference</p>
</td>
<td style="vertical-align:top; width:328px">
<p>Identifies the digital payment</p>
</td>
</tr>
<tr>
<td style="vertical-align:top; width:241px">
<p>Payment date</p>
</td>
<td style="vertical-align:top; width:328px">
<p>Records when payment was processed</p>
</td>
</tr>
<tr>
<td style="vertical-align:top; width:241px">
<p>Payment status</p>
</td>
<td style="vertical-align:top; width:328px">
<p>Shows completed, pending, or failed</p>
</td>
</tr>
<tr>
<td style="vertical-align:top; width:241px">
<p>Reconciliation status</p>
</td>
<td style="vertical-align:top; width:328px">
<p>Shows whether records match</p>
</td>
</tr>
</tbody>
</table>
<p>This information does not need to be complicated. The main objective is to give authorized staff a consistent record to review.</p>
<p>A business processing 1,000 supplier transactions in a month could use this register to identify unresolved payments without searching through separate spreadsheets.</p>
<h2><strong>4. Track Payment Status Clearly</strong></h2>
<p>A payment request can move through several stages.</p>
<p>For example:</p>
<p><strong>Pending Approval → Approved → Processing → Completed → Reconciled</strong></p>
<p>Some transactions may fail or remain pending. Those records should be clearly marked so that staff do not treat them as completed payments.</p>
<p>Clear status tracking also helps procurement respond to supplier questions. Instead of asking finance to manually search for every payment, procurement can refer to the transaction reference and current status.</p>
<p>This is particularly useful when suppliers have different payment schedules or when a business handles a large number of invoices each month.</p>
<h2><strong>5. Set Clear Responsibilities Between Teams</strong></h2>
<p>Payment reconciliation works better when each department knows exactly what it is responsible for.</p>
<h3><strong>Procurement Team</strong></h3>
<p>Procurement can be responsible for:</p>
<ul>
<li>Supplier information</li>
<li>Purchase order details</li>
<li>Purchase approval</li>
<li>Goods or service confirmation</li>
<li>Invoice submission</li>
</ul>
<h3><strong>Finance Team</strong></h3>
<p>Finance can handle:</p>
<ul>
<li>Invoice verification</li>
<li>Payment approval</li>
<li>Payment processing</li>
<li>Accounting records</li>
<li>Bank or settlement reconciliation</li>
</ul>
<h3><strong>Management</strong></h3>
<p>Management can review:</p>
<ul>
<li>Large-value transactions</li>
<li>Outstanding payments</li>
<li>Unresolved discrepancies</li>
<li>Supplier payment trends</li>
<li>Exceptions requiring approval</li>
</ul>
<p>Clear roles reduce repeated work and make it easier to identify where a payment issue occurred.</p>
<h2><strong>6. Use Digital Payment Records for Faster Reconciliation</strong></h2>
<p>Paper-based payment records can make transaction searches difficult. Digital records provide searchable information such as payment date, amount, transaction reference, and status.</p>
<p>Businesses should review the reporting features available through their payment setup. When considering the best payment gateway Bangladesh option, companies should look beyond payment acceptance and review transaction reporting, settlement information, support, and integration requirements.</p>
<p>The payment system should fit the company's procurement and finance workflow rather than operate as a separate process.</p>
<h2><strong>7. Reconcile Payments on a Regular Schedule</strong></h2>
<p>Businesses do not need to wait until the end of the month to identify payment differences.</p>
<p>A regular reconciliation schedule can be based on transaction volume.</p>
<p>For example:</p>
<ul>
<li><strong>Daily:</strong> Review high-volume payment activity</li>
<li><strong>Weekly:</strong> Check pending and failed supplier payments</li>
<li><strong>Monthly:</strong> Match payment records with accounting and bank records</li>
<li><strong>Quarterly:</strong> Review recurring reconciliation issues</li>
</ul>
<p>Regular checks make it easier to investigate discrepancies while the related invoice and procurement information is still readily available.</p>
<p>A company can also create an exception list containing transactions that require additional review.</p>
<h2><strong>8. Review the Role of Payment Service Providers</strong></h2>
<p>The payment provider is one part of the overall reconciliation process. Procurement and finance teams still need internal controls for purchase approval, invoice verification, and accounting.</p>
<p>When selecting a <a href="https://eps.com.bd/about-us">payment gateway service provider in Bangladesh</a>, businesses should review transaction reporting, settlement procedures, supported payment channels, integration options, and customer support. The provider should be able to supply the transaction information required for the company's reconciliation process.</p>
<p>Companies should also consider whether an easy payment system in Bangladesh fits their supplier and internal payment requirements.</p>
<p>For businesses that use several payment channels, online payment methods in Bangladesh should be reviewed based on transaction volume, supplier requirements, reporting needs, and existing financial systems.</p>
<h2><strong>9. Handle International Supplier Payments Separately</strong></h2>
<p>International supplier payments may involve additional records compared with domestic transactions.</p>
<p>Finance teams may need to review:</p>
<ul>
<li>Currency</li>
<li>Exchange rate</li>
<li>Bank charges</li>
<li>Settlement date</li>
<li>Supplier country</li>
<li>Payment reference</li>
<li>Supporting documents</li>
</ul>
<p>An international payment gateway in Bangladesh may be relevant for certain cross-border payment requirements. Businesses should first confirm supported currencies, transaction types, settlement arrangements, and eligibility.</p>
<p>International transactions should have clear documentation so that procurement and finance can identify the exact supplier obligation connected with each payment.</p>
<h2><strong>10. Use Reconciliation Data to Find Repeated Problems</strong></h2>
<p>Payment reconciliation is not only about checking whether transactions match. The records can also show where payment problems occur repeatedly.</p>
<p>Finance managers can review:</p>
<ul>
<li>Number of invoice mismatches</li>
<li>Duplicate payment attempts</li>
<li>Failed transactions</li>
<li>Pending payments</li>
<li>Missing documents</li>
<li>Average resolution time</li>
<li>Unreconciled transaction value</li>
</ul>
<p>For example, if 30 out of 700 monthly supplier payments require additional investigation, the business can review why those cases occur.</p>
<p>Perhaps most problems come from incomplete purchase orders, incorrect supplier account details, or invoice amounts that do not match approved purchases.</p>
<p>These figures are illustrative and should be replaced with the company's own records when used for internal reporting.</p>
<h2><strong>How EPS Bangladesh Can Support Procurement Payment Requirements</strong></h2>
<p>A business payment process should connect payment activity with the company's wider financial workflow. Procurement teams need clear supplier and purchase information, while finance teams need reliable transaction records for payment verification and accounting.</p>
<p>Businesses can review <a href="https://eps.com.bd/procurement-payment-solutions">procurement payment gateway solutions in Bangladesh</a> from EPS Bangladesh to understand payment options relevant to procurement-related requirements.</p>
<p>Before choosing a payment solution, companies should document their existing workflow and identify where reconciliation takes the most time. They should also determine which transaction information finance needs for accounting and which information procurement needs for supplier communication.</p>
<h2><strong>Building a Better Procurement-Finance Payment Workflow</strong></h2>
<p>Digital payment reconciliation becomes easier when both teams use consistent references, follow the same approval rules, and maintain accurate transaction records.</p>
<p>A practical workflow can be built around five basic stages:</p>
<ol>
<li><strong>Procurement approval</strong> — Confirm the purchase and supplier.</li>
<li><strong>Invoice verification</strong> — Match the invoice with the purchase.</li>
<li><strong>Payment approval</strong> — Confirm the amount and supporting documents.</li>
<li><strong>Digital payment</strong> — Process and record the transaction.</li>
<li><strong>Reconciliation</strong> — Match the payment with procurement and finance records.</li>
</ol>
<p>Businesses can start with a simple payment register and regular reconciliation schedule. Once the basic process is working, they can review system integration and reporting options according to their transaction volume.</p>
<p>A well-organized reconciliation process gives procurement and finance teams a common view of payment activity. It also helps businesses identify discrepancies, answer supplier questions, maintain accounting records, and keep better control over business spending.</p>
<p> </p>
See less
Posted on October 11, 2026
How Online Payments Improve Record-Keeping for Consultants
Consultants deal with many financial details throughout the month, from client invoices and project fees to refunds, recurring payments and business expenses. When payments are collected manually through cash or scattered bank transfers, keeping every transaction properly recorded can become difficult. Using an online payment gateway in Bangladesh gives consultants a clearer way to record client payments and match transactions with invoices.
A digital payment process also gives consultants a...
...
See More →
<p>Consultants deal with many financial details throughout the month, from client invoices and project fees to refunds, recurring payments and business expenses. When payments are collected manually through cash or scattered bank transfers, keeping every transaction properly recorded can become difficult. Using an online payment gateway in Bangladesh gives consultants a clearer way to record client payments and match transactions with invoices.</p>
<p>A digital payment process also gives consultants a reliable transaction trail. Each payment can be connected with details such as the amount, date, payer and transaction status. Working with a<a href="https://eps.com.bd/about-us"> payment gateway service provider in Bangladesh</a> can help a consultancy maintain a more organized payment process while reducing the need for manual record updates.</p>
<p>For consulting firms that receive payments from several clients, a dedicated<a href="https://eps.com.bd/consultancy-services-payment-solutions"> payment gateway solution for consultancy services in Bangladesh</a> can make financial administration easier to manage. Instead of checking different payment channels separately, consultants can keep payment information in a more structured system and use it when preparing invoices, financial reports and client statements.</p>
<h2><strong>Why Financial Record-Keeping Matters for Consultants</strong></h2>
<p>Consulting businesses often operate differently from product-based companies. A consultant may charge by project, consultation session, milestone, retainer period or service package. This creates several payment dates and billing arrangements that need to be tracked carefully.</p>
<p>A missing payment entry can create problems later. A consultant may believe an invoice is unpaid when the client has already made the payment, or a payment may be recorded without being matched to the correct invoice.</p>
<p>Good financial records help answer basic business questions:</p>
<ul>
<li>Which clients have paid?</li>
<li>Which invoices are still outstanding?</li>
<li>How much revenue came from each project?</li>
<li>When did a particular payment arrive?</li>
<li>Which payments are recurring?</li>
<li>How much money entered the business during a specific month?</li>
<li>Are the amounts recorded in the accounting system correct?</li>
</ul>
<p>Online payments can make these questions easier to answer because transactions leave a digital record that can be reviewed when needed.</p>
<h2><strong>1. Every Client Payment Creates a Digital Record</strong></h2>
<p>Cash payments often require manual entry into a spreadsheet, notebook or accounting system. This creates an extra step where errors can occur.</p>
<p>An online transaction normally contains information such as the payment amount, transaction date, payment status and transaction reference. Consultants can use these details when updating their financial records.</p>
<p>For example, suppose a consultant sends an invoice for BDT 50,000 for a website strategy project. Once the client pays online, the transaction record can be checked against the invoice. The consultant can then mark the invoice as paid and retain the transaction reference for future records.</p>
<p>This creates a simple connection:</p>
<p><strong>Invoice → Payment → Transaction Reference → Accounting Record</strong></p>
<p>That connection becomes useful when reviewing several months of business activity.</p>
<h2><strong>2. Easier Invoice and Payment Matching</strong></h2>
<p>Invoice matching is one of the areas where digital payments can save administrative time.</p>
<p>Consultants may have 20, 50 or even hundreds of transactions across different projects. Manually identifying which payment belongs to which invoice can take considerable time, especially when several clients pay similar amounts.</p>
<p>A digital payment record gives the consultant another reference point. The transaction ID, client information and payment amount can be compared with the invoice details.</p>
<p>For example:</p>
<table cellspacing="0" style="border-collapse:collapse; width:532px">
<tbody>
<tr>
<td style="vertical-align:top; width:109px">
<p><strong>Invoice</strong></p>
</td>
<td style="vertical-align:top; width:113px">
<p><strong>Amount</strong></p>
</td>
<td style="vertical-align:top; width:149px">
<p><strong>Payment Status</strong></p>
</td>
<td style="vertical-align:top; width:161px">
<p><strong>Transaction Record</strong></p>
</td>
</tr>
<tr>
<td style="vertical-align:top; width:109px">
<p>INV-101</p>
</td>
<td style="vertical-align:top; width:113px">
<p>BDT 25,000</p>
</td>
<td style="vertical-align:top; width:149px">
<p>Paid</p>
</td>
<td style="vertical-align:top; width:161px">
<p>Available</p>
</td>
</tr>
<tr>
<td style="vertical-align:top; width:109px">
<p>INV-102</p>
</td>
<td style="vertical-align:top; width:113px">
<p>BDT 40,000</p>
</td>
<td style="vertical-align:top; width:149px">
<p>Pending</p>
</td>
<td style="vertical-align:top; width:161px">
<p>Not received</p>
</td>
</tr>
<tr>
<td style="vertical-align:top; width:109px">
<p>INV-103</p>
</td>
<td style="vertical-align:top; width:113px">
<p>BDT 60,000</p>
</td>
<td style="vertical-align:top; width:149px">
<p>Paid</p>
</td>
<td style="vertical-align:top; width:161px">
<p>Available</p>
</td>
</tr>
</tbody>
</table>
<p>This type of record makes monthly reconciliation easier and gives the consultant a clearer view of outstanding invoices.</p>
<h2><strong>3. Better Cash Flow Tracking</strong></h2>
<p>Cash flow is closely connected to the timing of client payments. A consultant may have BDT 300,000 worth of invoices but only BDT 180,000 actually received during the month.</p>
<p>Online payment records help separate billed revenue from money that has actually been received.</p>
<p>This distinction matters when planning salaries, software subscriptions, office costs, contractor payments and other business expenses.</p>
<p>For example:</p>
<ul>
<li>January invoices: BDT 450,000</li>
<li>January payments received: BDT 320,000</li>
<li>Outstanding invoices: BDT 130,000</li>
</ul>
<p>Instead of looking only at total invoices, the consultant can see the amount actually collected.</p>
<h2><strong>4. Easier Monthly Financial Reporting</strong></h2>
<p>Consultants often need monthly or quarterly reports to understand how their business is performing. These reports may include total income, unpaid invoices, project revenue and payment activity.</p>
<p>Having digital transaction records makes the information easier to collect.</p>
<p>A consultant can group payments by:</p>
<ul>
<li>Month</li>
<li>Client</li>
<li>Project</li>
<li>Service</li>
<li>Payment status</li>
<li>Transaction amount</li>
</ul>
<p>This can help create cleaner financial reports without relying entirely on handwritten notes or scattered payment confirmations.</p>
<h2><strong>5. Fewer Manual Data Entry Errors</strong></h2>
<p>Manual record-keeping creates several opportunities for mistakes.</p>
<p>A payment of BDT 35,000 could accidentally be entered as BDT 30,000. A transaction date could be entered incorrectly. A payment could also be recorded against the wrong client.</p>
<p>Digital payment records provide original transaction information that can be checked against accounting entries.</p>
<p>This does not remove the need for proper bookkeeping. Consultants should still review their records regularly. But having a digital transaction trail gives them better source information for that review.</p>
<h2><strong>6. Easier Expense and Revenue Reconciliation</strong></h2>
<p>Consultants need to compare money received with their invoices and business expenses. Reconciliation helps identify differences between expected and actual amounts.</p>
<p>For example, a consultant may have:</p>
<ul>
<li>Client payments: BDT 500,000</li>
<li>Refunds: BDT 20,000</li>
<li>Payment charges: BDT 8,000</li>
<li>Net amount received: BDT 472,000</li>
</ul>
<p>Keeping these details separate gives a more accurate picture of the business's financial position.</p>
<p>A clear transaction history can also help when an accountant reviews the business records.</p>
<h2><strong>7. Useful for Tax and Accounting Preparation</strong></h2>
<p>Proper financial records are useful when preparing tax documents and accounting reports. Consultants may need to review income from different clients across a financial year.</p>
<p>Instead of searching through emails, screenshots and bank messages, they can refer to organized payment records.</p>
<p>Bangladesh Bank's recent payment data shows how quickly digital payment activity is growing. Its FY2024–25 Annual Report states that interbank digital payment volume increased by 11.3% year over year, while transaction value increased by 4.9%.</p>
<p>Bangladesh Bank's data also shows that digital transaction volume reached 56% of total financial-system transactions by June 2024, up from 51% in December 2023.</p>
<p>For consultants, this wider shift toward digital transactions means maintaining accurate digital payment records is becoming increasingly relevant to day-to-day financial administration.</p>
<h2><strong>8. Multiple Payment Options Can Help Client Collections</strong></h2>
<p>Different clients may prefer different payment channels. Some may use cards, bank-based transfers or mobile financial services.</p>
<p>The availability of several online payment methods in Bangladesh can give consultants more ways to collect project fees without asking every client to follow the same payment process.</p>
<p>The important point is not simply accepting more payment types. The payment information should remain organized after the transaction is completed.</p>
<h2><strong>9. International Clients Need Better Payment Records</strong></h2>
<p>Consultants working with overseas clients have another layer of financial administration. They may receive payments in foreign currencies, work with clients across different countries and need to maintain records for each transaction.</p>
<p>An international payment gateway in Bangladesh can be relevant for businesses that need to accept payments from clients outside the country, subject to applicable banking, foreign-exchange and payment regulations.</p>
<p>For international consulting work, keeping records of the client, payment date, currency, amount and transaction reference can help maintain clearer financial documentation.</p>
<h2><strong>10. Choosing a Payment System for a Consulting Business</strong></h2>
<p>Consultants should look beyond the ability to simply accept a payment. The payment process should also support proper financial administration.</p>
<p>Before selecting a payment provider, consider:</p>
<ul>
<li>Available payment channels</li>
<li>Transaction reporting</li>
<li>Payment status information</li>
<li>Transaction references</li>
<li>Settlement information</li>
<li>Refund handling</li>
<li>Security measures</li>
<li>Integration options</li>
<li>Support for local and international clients</li>
<li>Compatibility with existing accounting processes</li>
</ul>
<p>The<a href="https://eps.com.bd/"> best payment gateway Bangladesh</a> businesses choose will depend on their client base, payment volume, services and reporting requirements.</p>
<h2><strong>Final Thoughts</strong></h2>
<p>Financial record-keeping does not have to become a monthly struggle for consultants. When payment information is captured digitally, it becomes easier to match invoices, check received payments, monitor outstanding amounts and prepare financial reports.</p>
<p>Bangladesh Bank's payment-system data also reflects continued growth in digital transactions. During January–June 2025, BEFTN handled more than 184 million transactions, while NPSB handled more than 84 million transactions, according to Bangladesh Bank's payment-platform data.</p>
<p>For a consulting business, the practical benefit is clear: every client payment can become part of a more organized financial record instead of remaining as a separate confirmation, message or manual entry.</p>
<p>A good payment process should therefore support both collecting money and keeping track of it. When these two activities work together, consultants have a clearer view of their revenue, outstanding invoices and overall financial activity.</p>
See less
Posted on October 04, 2026
How RMG Businesses Can Improve Employee Salary Disbursement Tracking
The ready-made garment industry involves a large workforce, multiple production units, factory locations, and regular salary disbursements. For finance and HR teams, paying employees is only one part of the task. They also need to confirm who has been paid, identify pending transactions, maintain records, and resolve payment-related questions.
As factories grow, managing salary payments through paper records, spreadsheets, or several disconnected payment channels can become difficult. A suita...
...
See More →
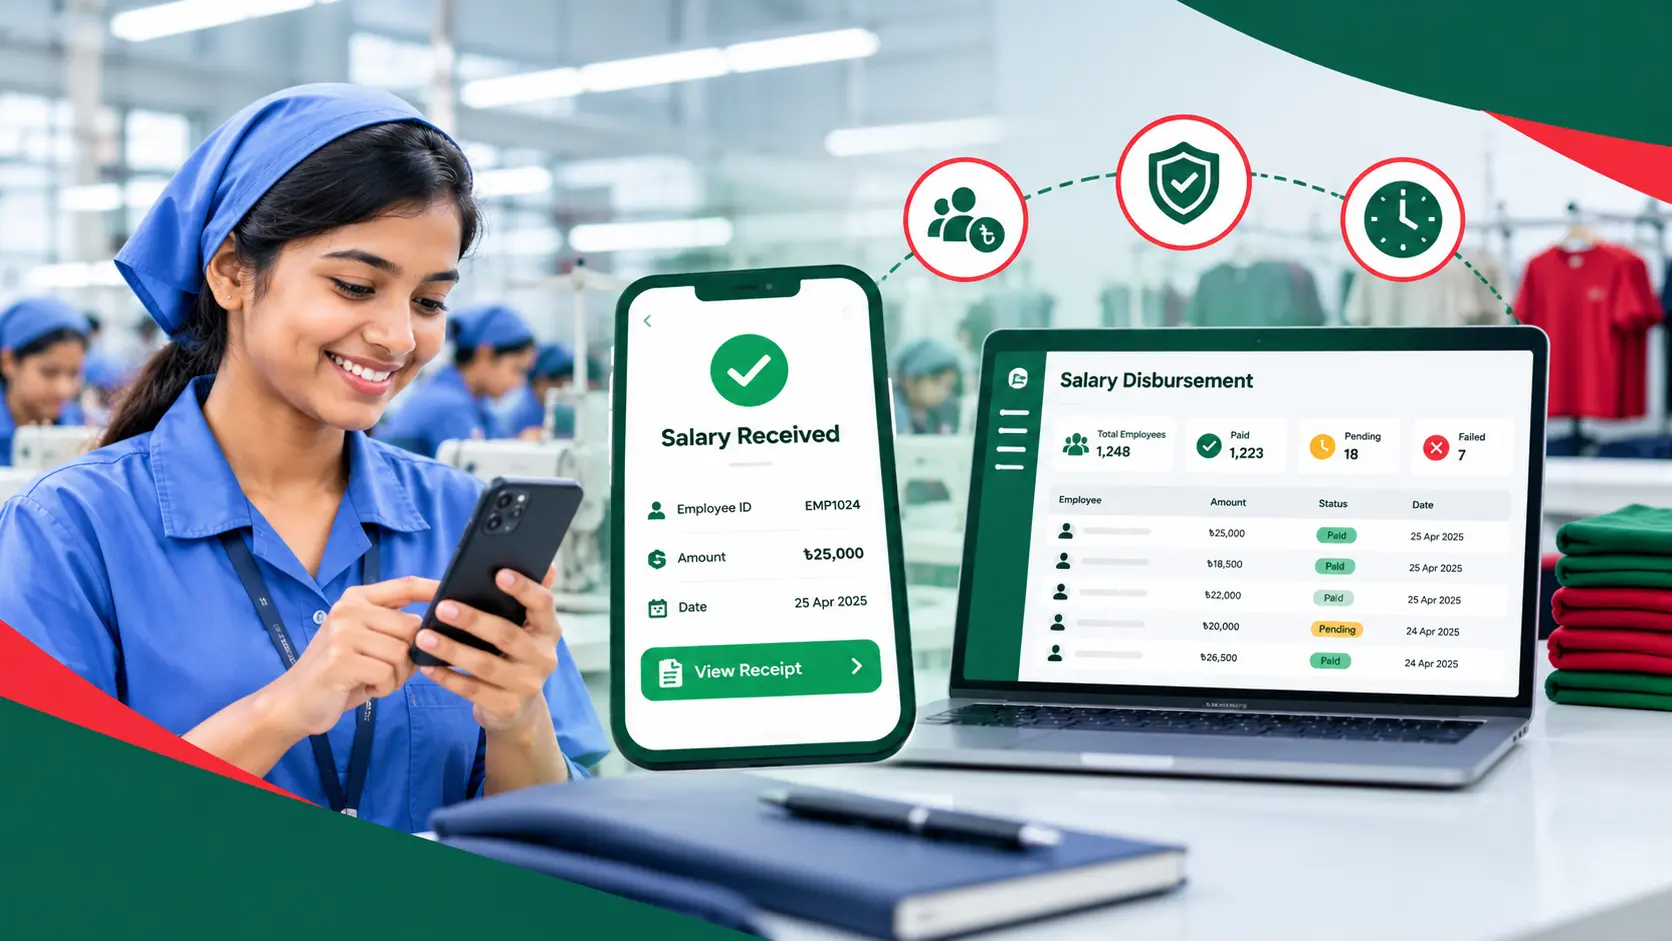
<p>The ready-made garment industry involves a large workforce, multiple production units, factory locations, and regular salary disbursements. For finance and HR teams, paying employees is only one part of the task. They also need to confirm who has been paid, identify pending transactions, maintain records, and resolve payment-related questions.</p>
<p>As factories grow, managing salary payments through paper records, spreadsheets, or several disconnected payment channels can become difficult. A suitable<a href="https://eps.com.bd/"> online payment gateway in Bangladesh</a> can form part of a broader digital payment process, giving businesses a structured way to manage transactions and payment records.</p>
<p>For garment manufacturers looking for sector-specific options,<a href="https://www.eps.com.bd/rmg-industry-payment-solutions"> RMG Industry Payment Gateway Solutions in Bangladesh</a> can support the broader payment requirements of the industry. A salary payment process should be planned around workforce size, payment frequency, employee information, financial controls, and the company's existing banking or payment arrangements.</p>
<p>This guide explains how RMG businesses can improve employee salary disbursement tracking and reduce the administrative difficulties that often come with large-scale salary payments.</p>
<h2><strong>Why Salary Disbursement Tracking Matters in RMG?</strong></h2>
<p>Salary payments are usually time-sensitive. Employees expect their wages to arrive according to the agreed payment schedule. A delay, incorrect amount, or unclear payment status can quickly create questions for HR and accounts teams.</p>
<p>A garment factory with 1,500 employees, for example, may need to process 1,500 salary transactions during a payment cycle. If even 2% of those transactions require manual checking, that means around 30 cases may need additional attention.</p>
<p>The 2% figure is an illustrative example, not an industry benchmark.</p>
<p>The larger the workforce, the more useful a structured tracking process becomes. Finance teams need to know:</p>
<ul>
<li>How many salary payments were initiated</li>
<li>How many were completed</li>
<li>Which transactions are pending</li>
<li>Which payments failed</li>
<li>Which employees require additional verification</li>
<li>Whether the total disbursed amount matches the payroll record</li>
</ul>
<p>A clear system can make these checks easier.</p>
<h3>1. Start With Accurate Employee Payroll Information</h3>
<p>Salary tracking begins before the payment is sent.</p>
<p>Employee information should be reviewed regularly so that payroll records contain the correct details. Depending on the organization's process, this may include:</p>
<ul>
<li>Employee name</li>
<li>Employee ID</li>
<li>Department</li>
<li>Factory or production unit</li>
<li>Salary amount</li>
<li>Bank or payment account details</li>
<li>Payment period</li>
<li>Relevant deductions</li>
<li>Payment status</li>
</ul>
<p>A small error in an account number or employee record can cause a payment to fail or reach the wrong destination.</p>
<p>RMG companies often have employees joining, leaving, changing departments, or moving between production units. Payroll information should reflect these changes before each salary cycle.</p>
<p>A defined approval process can also help. For example, the HR team can verify employee records while the accounts team checks salary amounts before the payment file or transaction batch is processed.</p>
<h3>2. Create a Single Salary Payment Record</h3>
<p>One of the common problems with manual salary management is that information may exist in different files.</p>
<p>The HR department may have one spreadsheet, accounts may maintain another record, and bank transaction information may be stored separately.</p>
<p>This makes reconciliation harder.</p>
<p><br />
</p>
<p>A centralized salary payment record can contain:</p>
<table cellspacing="0" style="border-collapse:collapse; width:546px">
<tbody>
<tr>
<td style="vertical-align:top; width:283px">
<p><strong>Information</strong></p>
</td>
<td style="vertical-align:top; width:263px">
<p><strong>Purpose</strong></p>
</td>
</tr>
<tr>
<td style="vertical-align:top; width:283px">
<p>Employee ID</p>
</td>
<td style="vertical-align:top; width:263px">
<p>Identifies the employee</p>
</td>
</tr>
<tr>
<td style="vertical-align:top; width:283px">
<p>Salary period</p>
</td>
<td style="vertical-align:top; width:263px">
<p>Shows which month or cycle was paid</p>
</td>
</tr>
<tr>
<td style="vertical-align:top; width:283px">
<p>Net salary</p>
</td>
<td style="vertical-align:top; width:263px">
<p>Confirms the payable amount</p>
</td>
</tr>
<tr>
<td style="vertical-align:top; width:283px">
<p>Transaction reference</p>
</td>
<td style="vertical-align:top; width:263px">
<p>Helps track the payment</p>
</td>
</tr>
<tr>
<td style="vertical-align:top; width:283px">
<p>Payment date</p>
</td>
<td style="vertical-align:top; width:263px">
<p>Records when payment was processed</p>
</td>
</tr>
<tr>
<td style="vertical-align:top; width:283px">
<p>Status</p>
</td>
<td style="vertical-align:top; width:263px">
<p>Shows successful, pending, or failed</p>
</td>
</tr>
<tr>
<td style="vertical-align:top; width:283px">
<p>Remarks</p>
</td>
<td style="vertical-align:top; width:263px">
<p>Records any special issue</p>
</td>
</tr>
</tbody>
</table>
<p>With these fields in one place, the accounts team can compare payroll data with payment information more easily.</p>
<h3>3. Use Digital Payment Channels for Salary Disbursement</h3>
<p>Digital payment channels can reduce the need for manual cash handling and paper-based records.</p>
<p>Before selecting a solution, RMG businesses should review the online payment methods in Bangladesh that are suitable for their payment requirements.</p>
<p>The appropriate choice depends on factors such as:</p>
<ul>
<li>Number of employees</li>
<li>Payment frequency</li>
<li>Employee access to banking or digital accounts</li>
<li>Transaction volume</li>
<li>Existing payroll systems</li>
<li>Settlement arrangements</li>
<li>Reporting requirements</li>
</ul>
<p>A factory may process several hundred or several thousand salary payments at once. The payment process should give the finance team enough information to identify individual transactions and review their status.</p>
<p>The goal is not simply to send money digitally. The business also needs a reliable record of what happened after each payment was initiated.</p>
<h3>4. Track Payment Status After Disbursement</h3>
<p>Sending a salary payment does not necessarily mean the payment process is finished.</p>
<p>Finance teams should be able to identify whether a transaction is:</p>
<ul>
<li>Successful</li>
<li>Pending</li>
<li>Failed</li>
<li>Returned</li>
<li>Under review</li>
</ul>
<p>Suppose a factory sends 2,000 salary payments and its payment records show 1,970 successful transactions, 20 pending transactions, and 10 failed transactions. The accounts team immediately knows which 30 cases require attention.</p>
<p>This example demonstrates the value of transaction-level tracking. The figures are illustrative and should not be treated as an industry statistic.</p>
<p>Without status information, staff may need to manually compare bank records, payroll files, employee complaints, and payment confirmations.</p>
<h3>5. Match Payroll Data With Transaction Records</h3>
<p>Reconciliation is one of the most important parts of salary disbursement tracking.</p>
<p>The payroll system may show that an employee should receive ৳25,000. The payment record should then show a corresponding transaction for that employee and amount.</p>
<p>The accounts team can compare:</p>
<p>Payroll amount → Payment amount → Transaction status → Settlement record</p>
<p>If the figures do not match, the team can investigate before closing the salary cycle.</p>
<p>For a factory processing 1,500 salaries, even a small number of mismatches can create extra administrative work. A structured reconciliation process helps staff identify those cases without checking every transaction manually from the beginning.</p>
<p>Businesses should also keep records of corrections and adjustments so that there is a clear history of what happened.</p>
<h3>6. Give Employees Clear Payment Confirmation</h3>
<p>Employees may contact HR when they are unsure whether their salary has been processed.</p>
<p>A clear payment confirmation process can reduce repeated questions.</p>
<p>Depending on the payment setup, employees may receive:</p>
<ul>
<li>Transaction confirmation</li>
<li>Payment reference</li>
<li>Payment date</li>
<li>Salary amount</li>
<li>Digital receipt or notification</li>
</ul>
<p>The information should be easy to understand.</p>
<p>For example, instead of simply showing "Transaction Completed," a payment notification could include the payment date, reference number, and relevant salary period.</p>
<p>This gives employees information they can refer to when contacting HR or accounts.</p>
<h3>7. Create a Process for Failed Salary Payments</h3>
<p>Failed salary transactions require quick attention because they directly affect employees.</p>
<p>RMG businesses should define what happens when a salary payment does not reach an employee.</p>
<p>A simple process can include:</p>
<ol>
<li>Identify the failed transaction.</li>
<li>Check the employee's payment information.</li>
<li>Confirm the reason or transaction status.</li>
<li>Correct the relevant information if required.</li>
<li>Reprocess the payment according to internal approval rules.</li>
<li>Record the action taken.</li>
<li>Confirm the updated status.</li>
</ol>
<p>The employee should also receive appropriate communication when a payment issue is being reviewed.</p>
<p>A written process reduces confusion between HR, accounts, factory management, and the employee concerned.</p>
<h3>8. Keep Access to Salary Information Controlled</h3>
<p>Salary information is sensitive business and employee data. RMG businesses should carefully control who can view or change payroll and payment records.</p>
<p>Access can be assigned according to job responsibilities.</p>
<p>For example:</p>
<ul>
<li>HR may manage employee information.</li>
<li>Accounts may process and reconcile salary payments.</li>
<li>Factory management may access selected reports.</li>
<li>Senior management may review summary information.</li>
</ul>
<p>User accounts should be reviewed when employees change roles or leave the organization.</p>
<p>Businesses should also keep a record of important changes to payroll information where the system supports such functionality.</p>
<h3>9. Review the Payment Process After Every Salary Cycle</h3>
<p>A salary payment cycle provides useful information about what worked and what caused problems.</p>
<p>After each cycle, the finance or payroll team can review:</p>
<ul>
<li>Total number of employees paid</li>
<li>Total salary amount</li>
<li>Failed transactions</li>
<li>Pending transactions</li>
<li>Reconciliation differences</li>
<li>Employee payment complaints</li>
<li>Time spent resolving payment issues</li>
</ul>
<p>Suppose a company processes 1,800 salary transactions and receives 25 payment-related complaints during one cycle. The team can categorize those complaints to identify repeated issues.</p>
<p>Perhaps 12 were related to payment confirmation, 8 were related to account information, and 5 involved other issues. Such internal data can show where process changes may be useful.</p>
<p>These numbers are examples rather than reported RMG industry statistics.</p>
<h3>10. Select a Payment Provider That Fits RMG Requirements</h3>
<p>Payment requirements can differ from one garment business to another. A small factory and a large group with several production units may need different payment arrangements.</p>
<p>When reviewing a payment gateway service provider in Bangladesh, RMG businesses should ask about:</p>
<ul>
<li>Transaction capacity</li>
<li>Payment channels</li>
<li>Transaction reporting</li>
<li>Settlement process</li>
<li>Payment confirmation</li>
<li>Support availability</li>
<li>Integration requirements</li>
<li>Security procedures</li>
</ul>
<p>Businesses should also understand the provider's terms and conditions before starting salary-related transactions.</p>
<p>The best payment gateway Bangladesh option for one company may not necessarily be the right choice for another. The decision should be based on workforce size, payment volume, existing financial processes, and the type of payment service required.</p>
<h2><strong>What About International Employees or Overseas Transactions?</strong></h2>
<p>Most employee salary payments in RMG factories are domestic. Some companies, especially groups with international operations, may also have overseas payment requirements.</p>
<p>If your organization needs to make or receive international transactions, review whether an international payment gateway in Bangladesh fits the intended use case.</p>
<p>Before selecting such a service, check:</p>
<ul>
<li>Supported countries</li>
<li>Supported currencies</li>
<li>Settlement process</li>
<li>Business eligibility</li>
<li>Transaction conditions</li>
<li>Verification requirements</li>
</ul>
<p>International payment facilities should only be included when they match actual business needs.</p>
<h2><strong>Build a Better Salary Tracking Process</strong></h2>
<p>A digital salary disbursement process is not only about sending employee payments. It also involves accurate payroll information, transaction records, payment confirmation, reconciliation, failed-payment handling, and controlled access.</p>
<p>RMG businesses can start by mapping their current salary process and identifying where manual work takes the most time. The next step is to define the information that HR and accounts teams need before, during, and after every salary cycle.</p>
<p>An easy payment system in Bangladesh can support this process when it is selected according to the company's workforce, transaction requirements, and existing financial operations.</p>
<p>For RMG businesses, the aim should be a payment process where employees receive clear payment information and finance teams can quickly identify successful, pending, and failed transactions.</p>
<p>With proper planning, digital records, and a payment setup that fits the company's requirements, salary disbursement tracking can become a more organized part of the overall payroll process. EPS Bangladesh provides payment solutions for different business sectors, including the RMG industry, allowing businesses to review payment services according to their specific operational requirements.</p>
See less
Posted on September 28, 2026
Manage News & Blogs
| Title | Content | Image | Actions |
|---|---|---|---|
| ব্যবসার জন্য পেমেন্ট গেটওয়ে কেন প্রয়োজন? | অনলাইন পেমেন্টের ১০টি গুরুত্বপূর্ণ সুবিধা: বাংল... |
|
|
| Key Payment Reporting Requirements for Financial Technology Businesses | Payment reporting is a core part of financial tech... |
|
|
| Digital Payment Reconciliation Between Procurement and Finance Teams | Procurement and finance teams are closely connecte... |
|
|
| How Online Payments Improve Record-Keeping for Consultants | Consultants deal with many financial details throu... |
|
|
| How RMG Businesses Can Improve Employee Salary Disbursement Tracking | The ready-made garment industry involves a large w... |
|
|